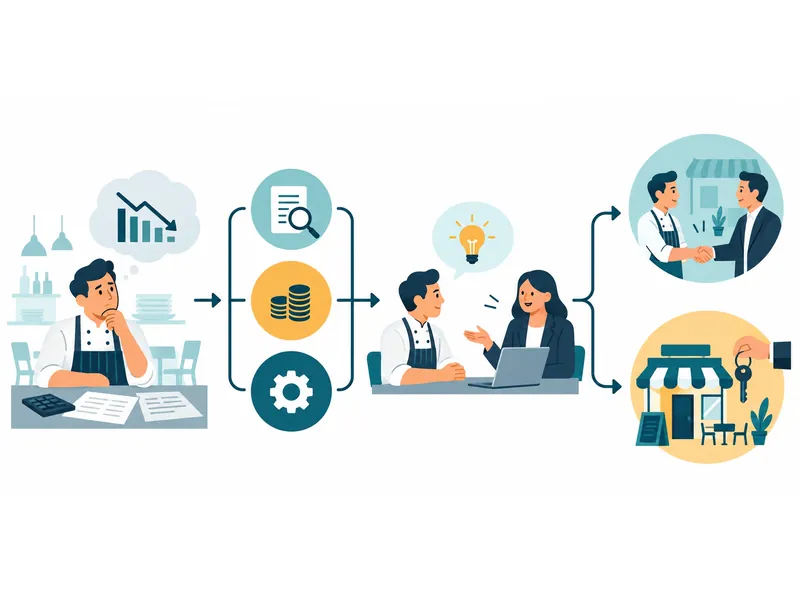
When a restaurant faces financial difficulty, owners should understand the position and available choices before committing to a rushed sale. Gather current cash-flow records, debts, lease obligations, payroll and tax filings, then speak promptly with qualified legal and accounting advisers. You can review restaurant sale listings to understand how businesses are presented, but another listing does not establish your value.
Map the immediate obligations
List due dates, secured debts, supplier balances, employee obligations, taxes and lease conditions. Separate verified amounts from estimates and identify who has authority to approve a sale, partnership or restructuring. Do not hide material facts from a prospective buyer or lender.
Compare a sale with other paths
Discuss whether an asset sale, share sale, investment, partner arrangement or operational change is feasible. Each option can have different creditor, tax, employment and landlord consequences. A business broker may explain the marketing process, while a lawyer and accountant should advise on structure and disclosure. A confidentiality plan can protect staff and customer relationships during authorized discussions.
Prepare a factual information package
Organize financial statements, sales support, lease and permit documents, equipment records and known issues. Give advisers time to identify gaps before information reaches buyers. Our buyer’s due-diligence guide shows the records purchasers commonly need to assess.
This is general information, not insolvency, legal, tax or financial advice.